

*/

© Henry Dannell
Exclusive Q&A with Kem Kemal of Henry Dannell
Yes. Some lenders rely on finalised tax calculations (SA302s), but others will accept finalised sole trader accounts from your accountant. This flexibility allows barristers to present a more accurate income picture and maximise borrowing potential.
Yes, although it’s not standard across all lenders. Some will consider projected income if you have a proven track record of growth and supporting evidence from chambers.
Yes. Some lenders will underwrite based on accounts rather than relying solely on tax returns, which can maximise borrowing potential, particularly if your accounts show a higher income.
Not necessarily. While many lenders prefer two years of accounts, some specialist lenders offer mortgages with just one year’s accounts, benefitting newer barristers.
The amount varies between lenders, as each has its own affordability model and assessment method. Income, outgoings, and financial commitments are key factors. Working with a mortgage adviser familiar with barristers’ needs can help secure better terms.
Yes. Some lenders may base their decision solely on your latest year’s accounts, especially if they show significant growth. Bespoke lenders often take a holistic view of your finances.
Typically, you’ll need:
High street lenders often use stringent assessments, but bespoke lenders understand fluctuations in barristers’ income. Providing a comprehensive income trajectory can mitigate credit risk concerns.
Not necessarily. The process differs due to income fluctuations, but lenders familiar with barristers’ circumstances are often more flexible in their policies.
Technically, none. Some lenders offer mortgages to barristers with little or no trading history, even during pupillage.
Yes, subject to meeting certain criteria. Some lenders require a minimum income or property equity. Interest-only mortgages can be useful for managing fluctuating income.
Lenders typically assess income based on your latest and previous tax calculations or accounts. They may consider childcare costs when calculating affordability. Holistic lenders can account for income reductions if you plan to return to work.
Offset mortgages reduce interest by offsetting savings against your mortgage balance, which is especially useful for barristers using tax funds to manage interest costs.
Yes. Some lenders offer mortgages based on pupillage awards, recognising future earning potential.
Yes. Lenders may include sporadic judicial work in their assessments if there’s evidence of income or a contract.
At Henry Dannell, we work closely with barristers at all stages of your career to ensure that lenders fully understand your unique income structure. We have exclusive pilot schemes with lenders specialising in professional mortgages who understand the nuances of barristers’ earnings, such as fluctuating income and aged debt. These tailored solutions can improve your mortgage options and help secure better terms. Our advisers are dedicated to providing bespoke guidance and giving you access to lenders who understand your profession’s unique financial profile.
Have more questions or want to explore your mortgage options? Visit our dedicated Barrister Portal. Book a personalised consultation with one of our expert advisers for tailored support. You can also explore our expert insights, make use of our mortgage calculators, and benefit from our 24/7 mortgage review service.
info@henrydannell.co.uk
0204 599 9444
www.henrydannell.co.uk
Disclaimer
A mortgage is secured against your home. Your home may be repossessed if you do not keep up repayments on your mortgage or any other debt secured on it. Mortgage deals may not be available, and lending is subject to individual circumstances and status.
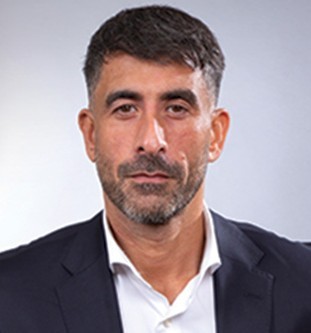
Kem Kemal is Co-Founder and CEO of Henry Dannell.
Yes. Some lenders rely on finalised tax calculations (SA302s), but others will accept finalised sole trader accounts from your accountant. This flexibility allows barristers to present a more accurate income picture and maximise borrowing potential.
Yes, although it’s not standard across all lenders. Some will consider projected income if you have a proven track record of growth and supporting evidence from chambers.
Yes. Some lenders will underwrite based on accounts rather than relying solely on tax returns, which can maximise borrowing potential, particularly if your accounts show a higher income.
Not necessarily. While many lenders prefer two years of accounts, some specialist lenders offer mortgages with just one year’s accounts, benefitting newer barristers.
The amount varies between lenders, as each has its own affordability model and assessment method. Income, outgoings, and financial commitments are key factors. Working with a mortgage adviser familiar with barristers’ needs can help secure better terms.
Yes. Some lenders may base their decision solely on your latest year’s accounts, especially if they show significant growth. Bespoke lenders often take a holistic view of your finances.
Typically, you’ll need:
High street lenders often use stringent assessments, but bespoke lenders understand fluctuations in barristers’ income. Providing a comprehensive income trajectory can mitigate credit risk concerns.
Not necessarily. The process differs due to income fluctuations, but lenders familiar with barristers’ circumstances are often more flexible in their policies.
Technically, none. Some lenders offer mortgages to barristers with little or no trading history, even during pupillage.
Yes, subject to meeting certain criteria. Some lenders require a minimum income or property equity. Interest-only mortgages can be useful for managing fluctuating income.
Lenders typically assess income based on your latest and previous tax calculations or accounts. They may consider childcare costs when calculating affordability. Holistic lenders can account for income reductions if you plan to return to work.
Offset mortgages reduce interest by offsetting savings against your mortgage balance, which is especially useful for barristers using tax funds to manage interest costs.
Yes. Some lenders offer mortgages based on pupillage awards, recognising future earning potential.
Yes. Lenders may include sporadic judicial work in their assessments if there’s evidence of income or a contract.
At Henry Dannell, we work closely with barristers at all stages of your career to ensure that lenders fully understand your unique income structure. We have exclusive pilot schemes with lenders specialising in professional mortgages who understand the nuances of barristers’ earnings, such as fluctuating income and aged debt. These tailored solutions can improve your mortgage options and help secure better terms. Our advisers are dedicated to providing bespoke guidance and giving you access to lenders who understand your profession’s unique financial profile.
Have more questions or want to explore your mortgage options? Visit our dedicated Barrister Portal. Book a personalised consultation with one of our expert advisers for tailored support. You can also explore our expert insights, make use of our mortgage calculators, and benefit from our 24/7 mortgage review service.
info@henrydannell.co.uk
0204 599 9444
www.henrydannell.co.uk
Disclaimer
A mortgage is secured against your home. Your home may be repossessed if you do not keep up repayments on your mortgage or any other debt secured on it. Mortgage deals may not be available, and lending is subject to individual circumstances and status.
Exclusive Q&A with Kem Kemal of Henry Dannell

The Chair of the Bar reports back
By Kem Kemal, CEO, Henry Dannell
By BSK Financial Planning
Mário Barroso, Head of R&D and Method Development at AlphaBiolabs
Susie Griffin on the admin that keeps barristers from billable work
Clement Cowley, Partner at The Penny Group, explains how global events can influence the performance of pensions and ISAs, and why taking a long-term approach to investing is often the most effective strategy
Kick off your career at the Bar Council’s Pupillage Fair this October – it’s one of the most valuable opportunities for aspiring barristers, says Amelia Clegg
Join us on Saturday 21 November 2026 at Leeds Beckett University and see for yourself why the North continues to be an exceptional place to build a career at the Bar
The golden age of advocacy? David Langwallner pays homage to the filmic if contentious barrister Sir Edward Carson and some of his contemporaries
Henry Fingerhut outlines what the Bar Standards Board AI guidance means for early career barristers
Not yet, says Jacob Turner. Regulation, unlike the technology itself, is a domain the legal profession can still control