

*/

© Henry Dannell
By Kem Kemal of Henry Dannell
For many barristers, securing a mortgage can be an unexpectedly complex process. Unlike salaried employees, your income is structured in a way that lenders often struggle to assess due to self-employment, fluctuating case-based earnings, or a bespoke tax structure.
While high street lenders can apply rigid affordability criteria, there are specialist lenders who understand the nuances of a barrister’s career.
If you’ve ever had a mortgage application declined despite strong earnings, it was likely due to a lender applying a standard assessment approach that didn’t reflect your financial reality. In many cases, this rejection was unnecessary.
A bit like a day in court, this is where specialist advice and expertise make all the difference.
Working with an adviser who understands both the legal profession and lender criteria ensures that your income is presented in the most effective way – maximising your borrowing potential.
The challenge: A newly qualified barrister, recently moved from pupillage to tenancy, wanted to secure a mortgage but had only one year of tax records.
The solution: Instead of using standard self-employed lending criteria, we placed the mortgage with a lender who accepted projected earnings and recent chambers records as proof of income.
The result: The client successfully secured a mortgage on competitive terms without having to wait for two full years of trading history.
The challenge: A senior barrister earning through both chambers and as a fee-paid judge was struggling to get a mortgage approved because different lenders assessed each income stream inconsistently.
The solution: We positioned the client’s finances holistically, presenting a comprehensive view of their combined earnings to a lender familiar with barristers’ income structures.
The result: The client was able to borrow at a higher multiple, securing a mortgage at the level required.
Many barristers structure their income for tax efficiency, and it’s common for their accounting periods to differ from the tax year. This can result in varying income figures across tax and accounting documents – potentially reducing affordability on paper, depending on what a lender chooses to review.
Because lenders assess income differently, a specialist mortgage adviser can help ensure your tax strategy doesn’t limit your borrowing. This may involve identifying lenders who accept chambers reports, recent figures, income projections, or a combination of sources.
Securing a mortgage as a barrister doesn’t have to be a frustrating process, but mainstream lenders don’t always recognise the true earning potential of legal professionals. Many barristers only seek advice after facing mortgage rejections, but proactive guidance can prevent those challenges altogether. At Henry Dannell, we work with lenders who recognise barristers’ career trajectories and earnings patterns – ensuring your financial profile is assessed correctly.
With expert guidance, securing the right mortgage becomes a seamless process rather than a stressful challenge.
Visit our dedicated Barrister Portal to book a personalised consultation with one of our expert advisers for tailored support. You can also explore our expert insights, make use of our mortgage calculators, and benefit from our 24/7 mortgage review service.
Disclaimer
A mortgage is secured against your home. Your home may be repossessed if you do not keep up repayments on your mortgage or any other debt secured on it. Mortgage deals may not be available, and lending is subject to individual circumstances and status.
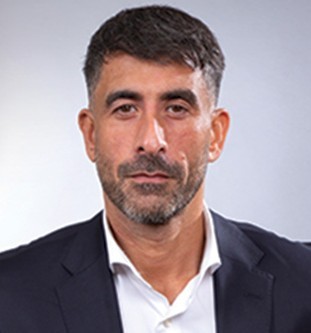
Kem Kemal is Co-Founder and CEO of Henry Dannell.
For many barristers, securing a mortgage can be an unexpectedly complex process. Unlike salaried employees, your income is structured in a way that lenders often struggle to assess due to self-employment, fluctuating case-based earnings, or a bespoke tax structure.
While high street lenders can apply rigid affordability criteria, there are specialist lenders who understand the nuances of a barrister’s career.
If you’ve ever had a mortgage application declined despite strong earnings, it was likely due to a lender applying a standard assessment approach that didn’t reflect your financial reality. In many cases, this rejection was unnecessary.
A bit like a day in court, this is where specialist advice and expertise make all the difference.
Working with an adviser who understands both the legal profession and lender criteria ensures that your income is presented in the most effective way – maximising your borrowing potential.
The challenge: A newly qualified barrister, recently moved from pupillage to tenancy, wanted to secure a mortgage but had only one year of tax records.
The solution: Instead of using standard self-employed lending criteria, we placed the mortgage with a lender who accepted projected earnings and recent chambers records as proof of income.
The result: The client successfully secured a mortgage on competitive terms without having to wait for two full years of trading history.
The challenge: A senior barrister earning through both chambers and as a fee-paid judge was struggling to get a mortgage approved because different lenders assessed each income stream inconsistently.
The solution: We positioned the client’s finances holistically, presenting a comprehensive view of their combined earnings to a lender familiar with barristers’ income structures.
The result: The client was able to borrow at a higher multiple, securing a mortgage at the level required.
Many barristers structure their income for tax efficiency, and it’s common for their accounting periods to differ from the tax year. This can result in varying income figures across tax and accounting documents – potentially reducing affordability on paper, depending on what a lender chooses to review.
Because lenders assess income differently, a specialist mortgage adviser can help ensure your tax strategy doesn’t limit your borrowing. This may involve identifying lenders who accept chambers reports, recent figures, income projections, or a combination of sources.
Securing a mortgage as a barrister doesn’t have to be a frustrating process, but mainstream lenders don’t always recognise the true earning potential of legal professionals. Many barristers only seek advice after facing mortgage rejections, but proactive guidance can prevent those challenges altogether. At Henry Dannell, we work with lenders who recognise barristers’ career trajectories and earnings patterns – ensuring your financial profile is assessed correctly.
With expert guidance, securing the right mortgage becomes a seamless process rather than a stressful challenge.
Visit our dedicated Barrister Portal to book a personalised consultation with one of our expert advisers for tailored support. You can also explore our expert insights, make use of our mortgage calculators, and benefit from our 24/7 mortgage review service.
Disclaimer
A mortgage is secured against your home. Your home may be repossessed if you do not keep up repayments on your mortgage or any other debt secured on it. Mortgage deals may not be available, and lending is subject to individual circumstances and status.
By Kem Kemal of Henry Dannell

The Chair of the Bar reports back
By Kem Kemal, CEO, Henry Dannell
By BSK Financial Planning
Mário Barroso, Head of R&D and Method Development at AlphaBiolabs
Susie Griffin on the admin that keeps barristers from billable work
Clement Cowley, Partner at The Penny Group, explains how global events can influence the performance of pensions and ISAs, and why taking a long-term approach to investing is often the most effective strategy
Kick off your career at the Bar Council’s Pupillage Fair this October – it’s one of the most valuable opportunities for aspiring barristers, says Amelia Clegg
The golden age of advocacy? David Langwallner pays homage to the filmic if contentious barrister Sir Edward Carson and some of his contemporaries
Henry Fingerhut outlines what the Bar Standards Board AI guidance means for early career barristers
The Ministry of Justice will match-fund up to 100 criminal pupillages, with grants available to criminal chambers across England and Wales. Similar to the COIC scheme, the grants will match-fund pupillages additional to those otherwise offered without government funding
Not yet, says Jacob Turner. Regulation, unlike the technology itself, is a domain the legal profession can still control